
Follow Us:
Understanding Your Credit for a Mortgage
Your credit report tells a story.
It's not the entire mortgage application, but it helps lenders understand how you've managed borrowed money in the past.
And when you're preparing for a mortgage, understanding that story can be extremely useful.
What Is a Credit Report?
A credit report generally contains information about your borrowing history, including accounts such as:
- credit cards
- loans
- lines of credit
- other reported credit obligations
It may show information about balances, payment history and account status. Lenders use credit information alongside income, down payment, property and other factors when evaluating a mortgage application.
Is Your Credit Score the Only Thing That Matters?
No.
A credit score can be important, but lenders don't necessarily evaluate borrowers using one number alone.
They may look at:
- payment history
- outstanding balances
- recent credit activity
- types of credit
- collections or past delinquencies
- the age and history of accounts
- overall debt obligations
Two borrowers with similar scores may still have very different credit profiles.
Should You Close Your Credit Cards Before Applying?
Not automatically. Changes to established credit accounts can affect your overall profile. Instead of making assumptions, speak with a mortgage professional before making significant changes if you're preparing for a mortgage.
Avoid New Debt Before Closing
One of the most important periods isn't just before your mortgage application. It's between approval and closing.
Financing a vehicle, increasing credit balances or taking on new debt can change your financial picture. A lender may require updated information before the mortgage funds.
So the safest purchase after getting your mortgage approval generally isn't a new truck for the driveway of the house you haven't closed on yet.
What If Your Credit Isn't Perfect?
Don't automatically assume homeownership is impossible.
Credit challenges can result from many situations.
The important thing is understanding:
- what appears on the report
- what happened
- how long ago it occurred
- what has happened since
- what options may be available today
The earlier you understand the issue, the more time you may have to address it.
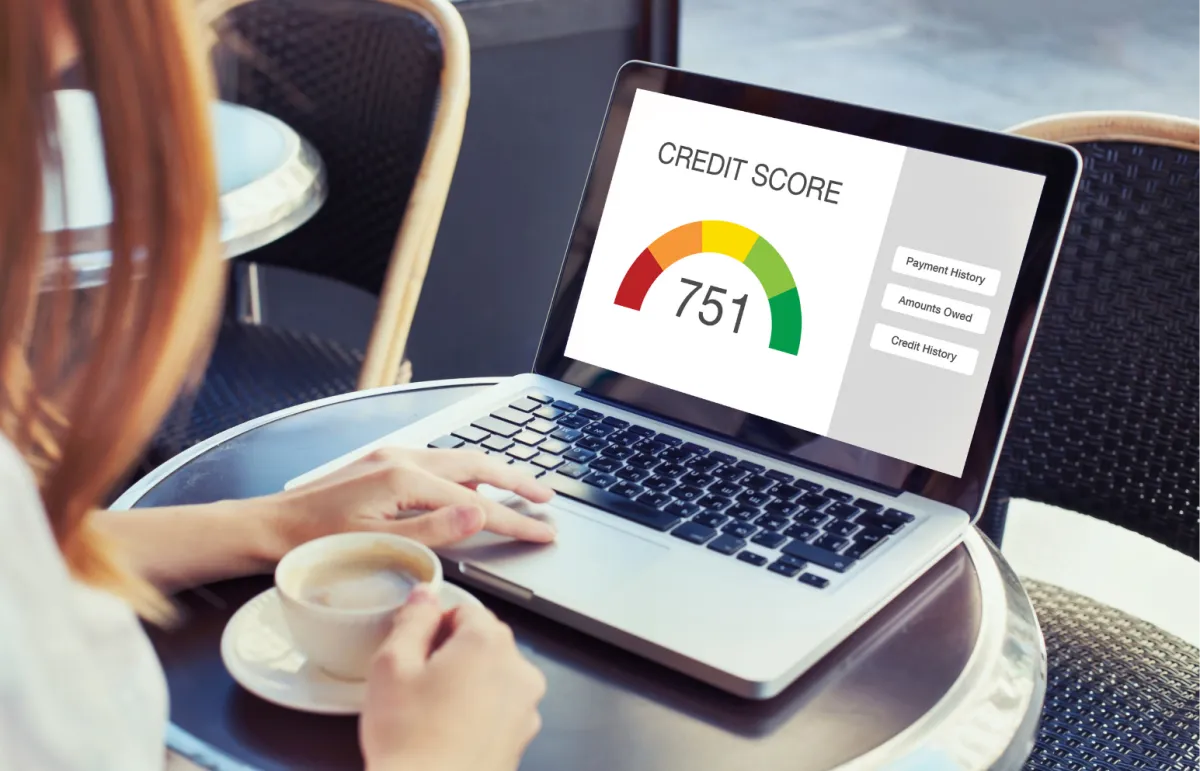
Make Credit Part of Your Mortgage Plan
If you're thinking of purchasing in six months or a year, that's not too early to start reviewing the financing side.
Sometimes the most valuable mortgage conversation happens long before a mortgage application is submitted.
Talk with Haystax Mortgage about building a mortgage-readiness plan. Find a Haystax Mortgage location here.
Why Work With Haystax Mortgage?
More than one lender. More than one option.
A bank can generally offer you its own mortgage products. A mortgage brokerage can explore options from a broader range of lenders.
But access to lenders is only part of the value.
A Haystax Mortgage professional can help you understand:
how different mortgage structures compare
which lender requirements may fit your situation
the trade-offs between rate and flexibility
penalties and prepayment privileges
how your mortgage fits your longer-term financial plans
You're at HOME with Haystax!
Frequently Asked Questions
What credit score do I need for a mortgage in Canada?
There is no single credit score that guarantees mortgage approval in Canada.
Different lenders and mortgage programs have different credit requirements, and a mortgage application is evaluated using more than the score alone. Lenders may also consider payment history, outstanding balances, recent inquiries, collections, bankruptcies, debt levels, income and down payment.
A stronger credit profile generally provides access to a broader range of mortgage options.
How does credit affect mortgage qualification?
Credit helps a lender assess how you have managed borrowed money in the past.
A lender may review your payment history, account balances, available credit, collections, missed payments and other information contained in your credit report.
Strong credit can provide access to more lenders and mortgage products, while credit challenges may reduce available options or result in additional conditions, higher costs or larger equity requirements.
What do mortgage lenders see on a credit report?
A mortgage lender may see information about your existing and previous credit accounts, payment history, balances, limits, credit inquiries and certain public or collection information reported to the credit bureau.
The report allows the lender to evaluate more than just your credit score.
For example, a high balance relative to available credit or a pattern of recent missed payments may be relevant even when the numerical score itself appears acceptable.
Can I get a mortgage with poor credit?
Possibly. Poor credit does not automatically make obtaining a mortgage impossible.
Available options will depend on factors such as the nature and age of the credit problems, income, down payment, property, current debt, recent repayment history and the lender's guidelines.
Borrowers who do not qualify through traditional prime lenders may have other mortgage options, although those alternatives can involve higher rates, fees or equity requirements.
Should I close credit cards before applying for a mortgage?
Not automatically.
Closing an established credit account can change your credit profile, available credit and credit-utilization ratio. In some situations, keeping an established account open with a low or zero balance can be preferable to closing it immediately.
If you're preparing for a mortgage, speak with a mortgage professional before making major changes to established credit accounts.
Ready to Talk About Your Mortgage?
No pressure, just clear answers, honest guidance, and a real person ready to help.
We look forward to connecting.
Send us a message
Follow Us
Follow Us
Mortgage Resources
Join Haystax
Ownership & Career Resources
Company
© Copyright 2026. Haystax Financial. All rights reserved.